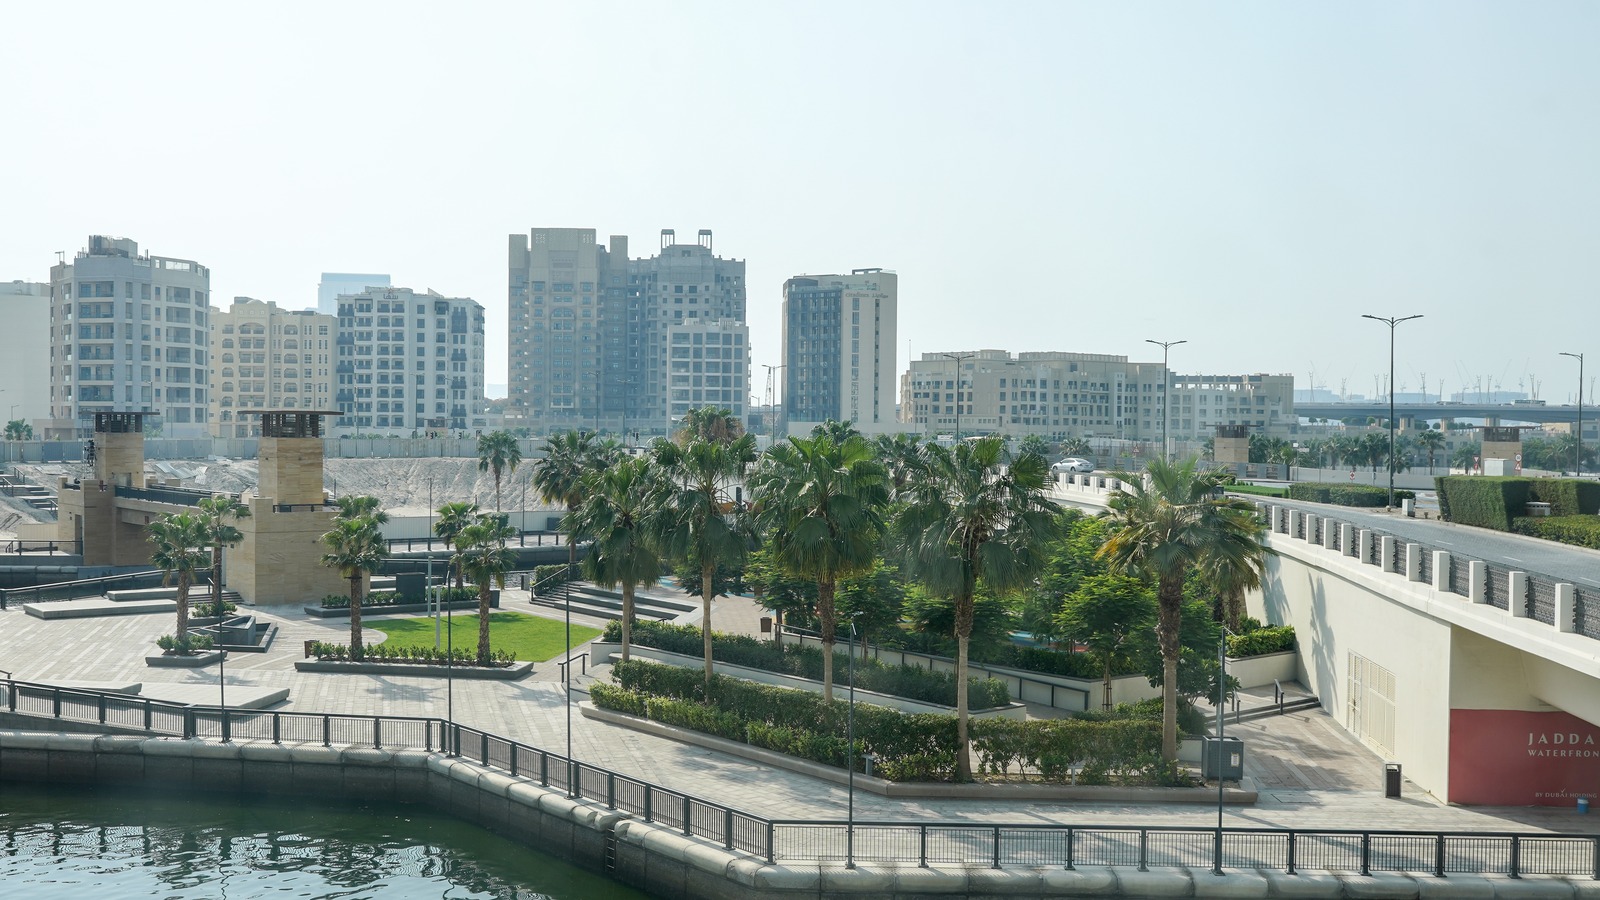
Image credit: Timothy A. Gonsalves / Wikimedia Commons (CC BY-SA 4.0). License: CC BY-SA 4.0.
Dubai’s mid-market hotels held up better than the luxury tier in the first half of 2026. Cavendish Maxwell’s hospitality readout puts Upper Midscale occupancy near 66 percent and Midscale near 64 percent, while Luxury averaged about 51 percent and Upper Upscale about 52 percent as regional airspace disruption and weaker international leisure demand hit the premium end hardest.
That split matters for anyone still pricing a Dubai stay for late 2026. Breaking Travel News and Arabian Business both report the same Cavendish Maxwell H1 figures, including a market-wide average occupancy of 56 percent, down about 30 percent year over year, and an average daily rate of AED701, down 7 percent.
- Upper Midscale occupancy: Nearly 66 percent in H1 2026, highest among tracked classes.
- Midscale occupancy: Almost 64 percent over the same six months.
- Luxury occupancy: About 51 percent; Upper Upscale about 52 percent.
- Market ADR: AED701 in H1, down 7 percent year over year.
- Traveler takeaway: Midscale inventory absorbed more domestic and regional demand than premium rooms.
What the H1 numbers actually say
Cavendish Maxwell’s Dubai Hospitality Sector H1 2026 Market Performance report is the primary data set behind the coverage. It measures hotel classes separately, which is why the mid-market outperformance is visible even though the whole city cooled.
Citywide occupancy averaged 56 percent from January through June. That is a sharp drop from the same stretch a year earlier, but consultants say the year-over-year gap narrowed after April as staycation campaigns and domestic promotions picked up. Rate discipline mattered too. ADR fell only 7 percent while occupancy fell much more, a sign operators preferred protecting price over filling every empty room at any cost.
Luxury still posted the highest room rates even after a 6.2 percent ADR decline. Upper Upscale rates were the most resilient, easing only about 2 percent. The story is not that luxury became cheap. It is that premium hotels left more rooms empty while midscale properties kept more keys filled.
Why midscale absorbed the shock better
Vidhi Shah of Cavendish Maxwell pointed to demand mix. Mid-market hotels draw more domestic, regional, and corporate travelers. Premium hotels lean harder on long-haul international leisure and higher-spending visitors, so flight disruptions and confidence shocks hit them first.
Confirmed fact: Upper Midscale and Midscale led H1 occupancy, while Luxury and Upper Upscale lagged. Supported interpretation: travelers who still moved around the Gulf or within the UAE kept choosing practical, mid-priced rooms over trophy properties when plans felt less certain.
Unknowns remain. Public summaries do not publish a brand-by-brand list, and they do not say how long any single hotel class will keep outperforming once long-haul flying fully normalizes. Treat class-level averages as planning context, not a guarantee for one specific property.
Supply, openings, and what is still coming
Three new Dubai hotels opened in H1, but closures and temporary renovation dark periods left overall supply slightly lower by mid-year. Cavendish Maxwell counted almost 152,140 rooms across 727 hotels at mid-2026, down 0.3 percent in rooms and 1 percent in hotels versus year-end 2025.
About 3,150 rooms are still scheduled for delivery by the end of 2026, which would push supply toward roughly 155,300 rooms. Another 2,580 rooms are due in 2027 and 2,470 in 2028. Premium classes still dominate the stock. Upscale, Upper Upscale, and Luxury together hold nearly 70 percent of rooms, which is why a premium soft patch shows up so clearly in citywide numbers.
If you are comparing neighborhoods for a winter trip, remember that inventory pressure and class mix vary by district. A midscale win citywide does not automatically mean every Marina or Downtown deal is better than every luxury rate. Check the specific hotel’s cancellation terms and the week you need.
What this means for travelers booking H2 and winter
Cavendish Maxwell expects occupancy to keep recovering later in 2026 if international travel returns with the events season and winter window. Emirates was described as operating near 85 percent of pre-conflict levels and adding capacity, which should help premium hotels that depend on long-haul arrivals. Government stimulus packages and campaigns such as Dubai Summer Surprises are also part of the recovery toolkit cited in the coverage.
For a practical booking decision, start with the class that matches your trip purpose. A family combining beach days with LEGOLAND Dubai may find midscale inventory both easier to fill and better aligned with H1 demand. Cruise passengers overnighting before or after a call at Dubai’s Mina Rashid cruise port should still compare transfer time and cancellation flexibility, then decide whether a premium rate is worth it while long-haul confidence is rebuilding.
Think about two concrete trip shapes. A three-night weekend built around malls, a theme park day, and a beach afternoon often does not need a luxury skyline suite, especially if breakfast and a flexible cancel window matter more than a butler. A seven-night winter holiday timed to major events may still justify premium if the hotel’s inclusions, location, and refund rules beat a cheaper midscale option after fees.
ADR guidance from the consultancy points to a year-end range around AED600 to AED675. That is a forecast band, not a live quote. Use it to judge whether a winter offer looks rich or reasonable against H1’s AED701 average, then verify the live rate and inclusions on the hotel’s own booking page.
Also separate occupancy from price. Midscale rooms filled more often in H1, but that does not mean every midscale rate is a bargain, and it does not mean luxury is empty tonight. It means the market’s demand cushion sat lower on the pyramid while long-haul leisure was soft. Re-check your dates after major airline capacity announcements, because premium recovery will likely move first when long-haul seats return.
- Class choice: Midscale and upper midscale held higher H1 occupancy than luxury and upper upscale.
- Rate lens: Citywide ADR was AED701 in H1; year-end guidance centers near AED600 to AED675.
- Winter watch: Recovery still hinges on restored long-haul flying and traveller confidence.
- Supply note: Thousands of new rooms are due through 2028, so compare flex rates carefully.
The plain reading is simple. In H1 2026, Dubai’s mid-market hotels kept more rooms busy than the premium tier while the city adjusted to weaker international leisure demand. If you are booking now, price the class that fits your itinerary, keep cancellation flexibility while H2 recovery is still unfolding, and do not assume last year’s luxury occupancy pattern still applies.
One last check before you pay: confirm whether breakfast, tourism dirhams, and resort fees are inside the quoted rate. H1 class averages hide those extras, and a midscale total can beat a naked luxury headline once fees land on the final invoice.
Which Dubai hotel class had the highest H1 2026 occupancy?
Upper Midscale led at nearly 66 percent, with Midscale close behind at almost 64 percent, according to Cavendish Maxwell.
How did luxury hotels perform against midscale in Dubai?
Luxury averaged about 51 percent occupancy and Upper Upscale about 52 percent, trailing the mid-market classes in H1 2026.
What was Dubai’s average hotel rate in the first half of 2026?
Average daily rate was AED701, down 7 percent from the same period a year earlier.
Are more Dubai hotel rooms still opening?
Yes. About 3,150 rooms are scheduled by the end of 2026, with more inventory planned for 2027 and 2028.
Should travelers avoid luxury hotels in Dubai right now?
No. Luxury can still fit the trip, but H1 data shows midscale rooms filled more reliably while long-haul demand was softer.