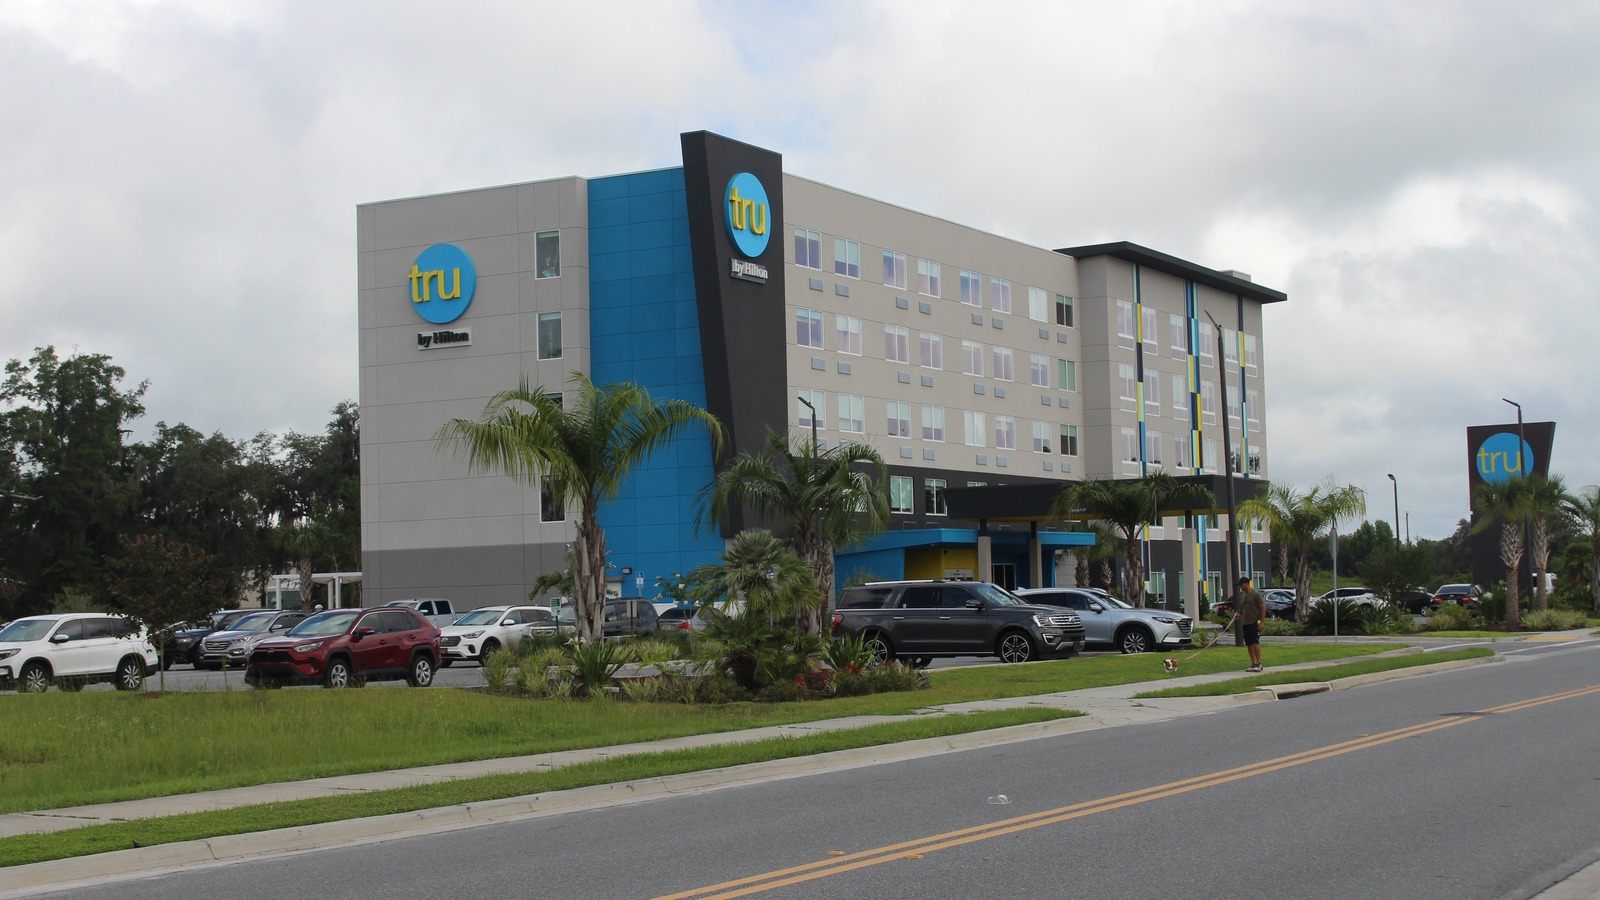
Image credit: Michael Rivera via Wikimedia Commons CC BY-SA 4.0. License: CC BY-SA 4.0.
United States hotel demand is running hotter than forecasters expected this year, and a large share of the surprise is not World Cup tourism. Travel Weekly reported on August 17, 2026, that CoStar and Tourism Economics raised their 2026 U.S. hotel outlook again, with analysts and hotel CEOs tying midscale strength to the AI data-center construction boom.
The traveler decision is practical. If you are booking work trips near major data-center corridors, or midweek rooms in industrial and exurban markets, price earlier and expect tighter midscale inventory while construction crews and project managers keep rooms full.
- Forecast: CoStar and Tourism Economics now project 4.4 percent U.S. RevPAR growth for 2026.
- Driver: AI data-center construction is lifting hotel demand outside top tourist hubs.
- Who feels it: Midscale and upper-midscale brands serving project workers and managers.
- Named brands: Hilton cited Hampton, Home2 Suites, and Tru among the rebound set.
- Why now: August 17 Travel Weekly synthesis of the reforecast and recent CEO earnings comments.
The reforecast is not only a World Cup story
CoStar and Tourism Economics upgraded the U.S. hotel forecast for the second time this year. Travel Weekly said the firms now project 2026 revenue per available room growth of 4.4 percent, average daily rate growth of 3.1 percent, and occupancy of 63.1 percent.
That follows a June revision that already lifted RevPAR expectations to 2.8 percent from a February base of only 0.6 percent growth. The speed of the revision is itself a signal. Aran Ryan of Tourism Economics told Travel Weekly it was unusual for February-to-July performance to force such a large upgrade.
Jan Freitag, national director of hospitality analytics for CoStar Group, said the industry understood World Cup host markets and the top 25 markets reasonably well. The miss was strength outside those markets. In other words, the upside is not only big-event city centers.
Where the AI construction demand actually shows up
Freitag had already argued in a February analysis that hotels near large AI data-center construction sites, often in suburban and exurban areas, enjoyed steady occupancy gains through 2025. He told Travel Weekly demand should remain elevated during construction phases.
He pointed to hotels near a project in Homer City in western Pennsylvania and a development near Abilene, Texas, as standout cases, with annualized occupancy increases exceeding 15 percent near those cities. The point is not that every U.S. traveler will feel a national sellout. It is that a thin hotel inventory within a few miles of a major site can reprice quickly.
“These data centers are often built in the middle of nowhere,” Freitag said, according to Travel Weekly. Extended-stay and midscale owners inside roughly a five-mile radius of those sites, he argued, are in an unusually strong position while construction lasts.
That construction-to-lodging link is not only a Travel Weekly observation. Hotel Dive reported in July 2026 that data-center projects are driving extended-stay demand nationwide during the build phase, citing industry executives and the scale of U.S. data-center construction spending.
That is the booking rule for travelers. If your site visit or contractor week sits next to a named campus build, do not assume last year’s midweek rate still exists two weeks out.
Hilton and Wyndham CEOs say midscale is the real surface
Hilton CEO Christopher Nassetta highlighted AI investment on the company’s second-quarter earnings call in late July, citing a single $500 billion data-center project in Kentucky as one example. Travel Weekly reported his view that once those projects are underway, the demand tailwind lasts for a period of time, and that “the middle class is getting back in the game.”
Nassetta also described the customer mix. People doing the work are not mainly filling luxury hotels. They are filling midscale and upper-midscale hotels. Hilton brands he linked to that rebound include Hampton, Home2 Suites, and Tru, which he said had swung from roughly 2 percent declines a year earlier to growth around 4 percent to 6 percent.
Wyndham Hotels and Resorts CEO Geoff Ballotti made a similar industrial-Midwest point on July 23. Travel Weekly reported RevPAR up 10 percent in Illinois and Indiana, 9 percent in Iowa, 7 percent in Wisconsin, and 6 percent in Ohio for Wyndham, with hotels in project-adjacent markets serving transportation, AI, data-center, and industrial builds.
Marriott CEO Anthony Capuano, on the company’s early August second-quarter call, said U.S. and Canada strength was “pervasive across chain scales,” with select-service RevPAR up more than 4 percent. Marriott select-service names in that conversation include Courtyard, Fairfield, and SpringHill Suites.
What this means if you are the traveler, not the analyst
Business travelers should treat midweek midscale rooms near active construction corridors as scarcity inventory. Book earlier than you would for a leisure weekend in a large coastal city, and keep a backup hotel one town over if the project market has only a handful of branded properties.
Leisure guests who only pass through those same corridors may see higher midweek rates than their last road-trip memory. That is not proof of a national leisure bubble. It is local project demand overlapping the nights you wanted a cheap Hampton or Tru stop.
Meeting planners and small-company teams should also note Freitag’s comment that small and midsize business spending is lifting upscale, upper-midscale, and midscale performance more than last year. Group business, he said, has bounced back after earlier tariff-related hesitation. That mix can tighten inventory even when leisure calendars look calm.
For a concrete business-hotel planning example in a dense midscale market, Deep Arrival’s hotels near the Orange County Convention Center guide is a useful model of how convention and project-style demand can shape room choice. For broader stay strategy when rates move, start from the where to stay planning hub.
Other forces still matter, and 2027 comps get harder
Ryan of Tourism Economics told Travel Weekly that broader household wealth, easing inflation, and a more balanced labor market also support demand. AI construction is a key driver in the current narrative, not the only driver. A smart traveler should not invent a data-center boom where the local market has no project.
Looking ahead, CoStar and Tourism Economics project 2027 RevPAR growth of 2.1 percent, with average daily rate growth slowing to 1.6 percent as inflation decelerates. Freitag framed that as growth on growth after a strong 2026, not a crash. U.S. supply growth is expected to be only about 0.5 percent this year, below the long-run average near 1.6 percent, which keeps inventory discipline on the hotel side.
For Texas trip planning in markets that often absorb industrial and tech travel, Deep Arrival’s Dallas things to do guide and Houston things to do guide remain the leisure-side companions if your work night turns into a weekend add-on. They do not replace a live hotel search near a specific data-center address.
None of this authorizes inventing a data-center story for a pure leisure beach trip. The useful filter is whether your dates and address sit near active construction logistics. If the answer is no, keep normal booking habits. If the answer is yes, treat the midscale layer as the constrained surface and move first.
Hotel investors may celebrate the same numbers that frustrate a last-minute traveler. For Deep Arrival readers, the only score that matters is whether the room you need is still available at a rate you will accept. The August reforecast is evidence that more people are competing for those rooms in more places than the winter models expected.
Keep receipts and flexible rate options when the project market is thin. A free cancellation window is often worth more than a small prepaid discount if the crew schedule shifts by two days.
- Project weeks: Book midscale rooms near active data-center sites earlier than leisure habit suggests.
- Brand set: Expect Hampton, Home2, Tru, and similar select-service names to feel the construction demand first.
- Backup plan: Keep an alternate hotel outside the five-mile project bubble when the local set is tiny.
- Rate reading: Higher midweek rates in exurban markets may be project demand, not a national leisure spike.
- 2027 view: Growth may slow after a strong 2026, but current construction cycles still matter for near-term trips.
The smart-neighbor takeaway is simple. America’s hotel year is beating the old forecast because money is moving into places that used to look quiet on a leisure map. If your trip depends on a midscale bed next to a big AI build, treat the room like limited inventory and lock it before the crews do.
How strong is the new 2026 U.S. hotel forecast?
Travel Weekly said CoStar and Tourism Economics now project 4.4 percent RevPAR growth, 3.1 percent ADR growth, and 63.1 percent occupancy for 2026 after a second upward revision this year.
Why do AI data centers affect hotel rooms?
Large construction projects bring multi-year crews and managers into suburban and exurban markets that often have limited midscale supply, which lifts occupancy and rates near the sites.
Which hotel types are seeing the demand?
Analysts and CEOs pointed to midscale and upper-midscale brands, including Hilton names such as Hampton, Home2 Suites, and Tru, plus broader select-service strength at other groups.
Is this only a World Cup story?
No. CoStar’s Freitag said the surprise was strength outside World Cup host markets and the usual top 25 markets.
What should a traveler do differently this week?
If your dates sit near an active data-center construction market, book the midscale room earlier, compare one backup hotel outside the immediate project radius, and recheck rates before you lock nonrefundable plans.